SIP vs Lump Sum in India: How to Choose for Your Financial Goals
In India, SIP suits disciplined, lower-risk investors and beginners, while lump sum fits those with immediate funds and higher risk tolerance aiming for larger returns.
Contents
- SIP versus lump-sum decision matrix
- What is the difference between SIP and lump sum investment in India?
- Which investment method is better for beginners: SIP or lump sum?
- How does market volatility affect SIP vs lump sum investments?
- What are the advantages of SIP over lump sum in Indian mutual funds?
- When should an investor choose lump sum investments in India?
- What financial goals are more suited to SIP investments?
- Are there tax benefits linked to SIP or lump sum investments in India?
- How does the investment horizon influence the choice between SIP and lump sum?
- How do returns compare between SIP and lump sum investments over the long term?
- Comparison Table: SIP vs Lump Sum Investments in India
- Frequently asked questions
- The bottom line
- Sources & methodology
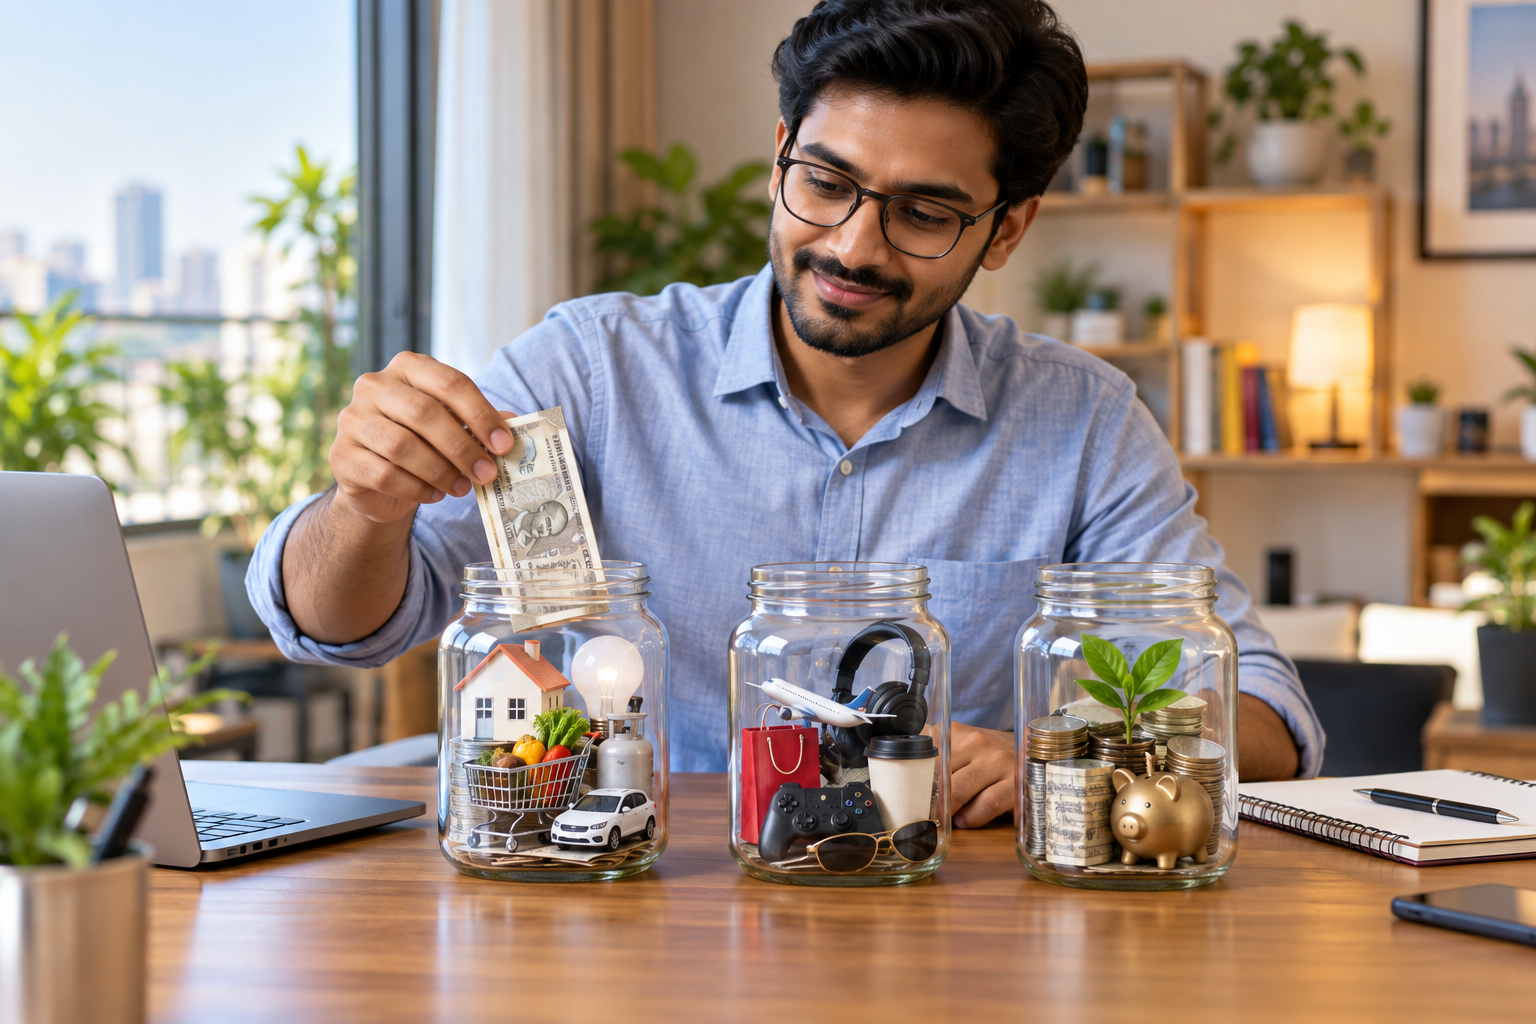
In India, choosing between SIP (Systematic Investment Plan) and lump sum investments depends on your risk appetite, investment horizon, and financial goals. SIPs offer regular, smaller investments that build wealth steadily and reduce market timing risk. Lump sum investments involve deploying a large amount at once, offering higher return potential but with greater exposure to market volatility.
SIP versus lump-sum decision matrix
| Question | SIP may fit when | Lump sum may fit when |
|---|---|---|
| Cash availability | Income arrives monthly | Investable cash is already available |
| Timing concern | You want to spread entry dates | You accept immediate market exposure |
| Behaviour | Automation improves discipline | You can follow a documented allocation plan |
| Goal horizon | Regular contributions match the goal | The full amount has the same long horizon |
Compare scenarios using the same assumed return, fees, tax treatment and end date. Illustrations are not forecasts; suitability depends on risk capacity and the chosen investment.
What is the difference between SIP and lump sum investment in India?
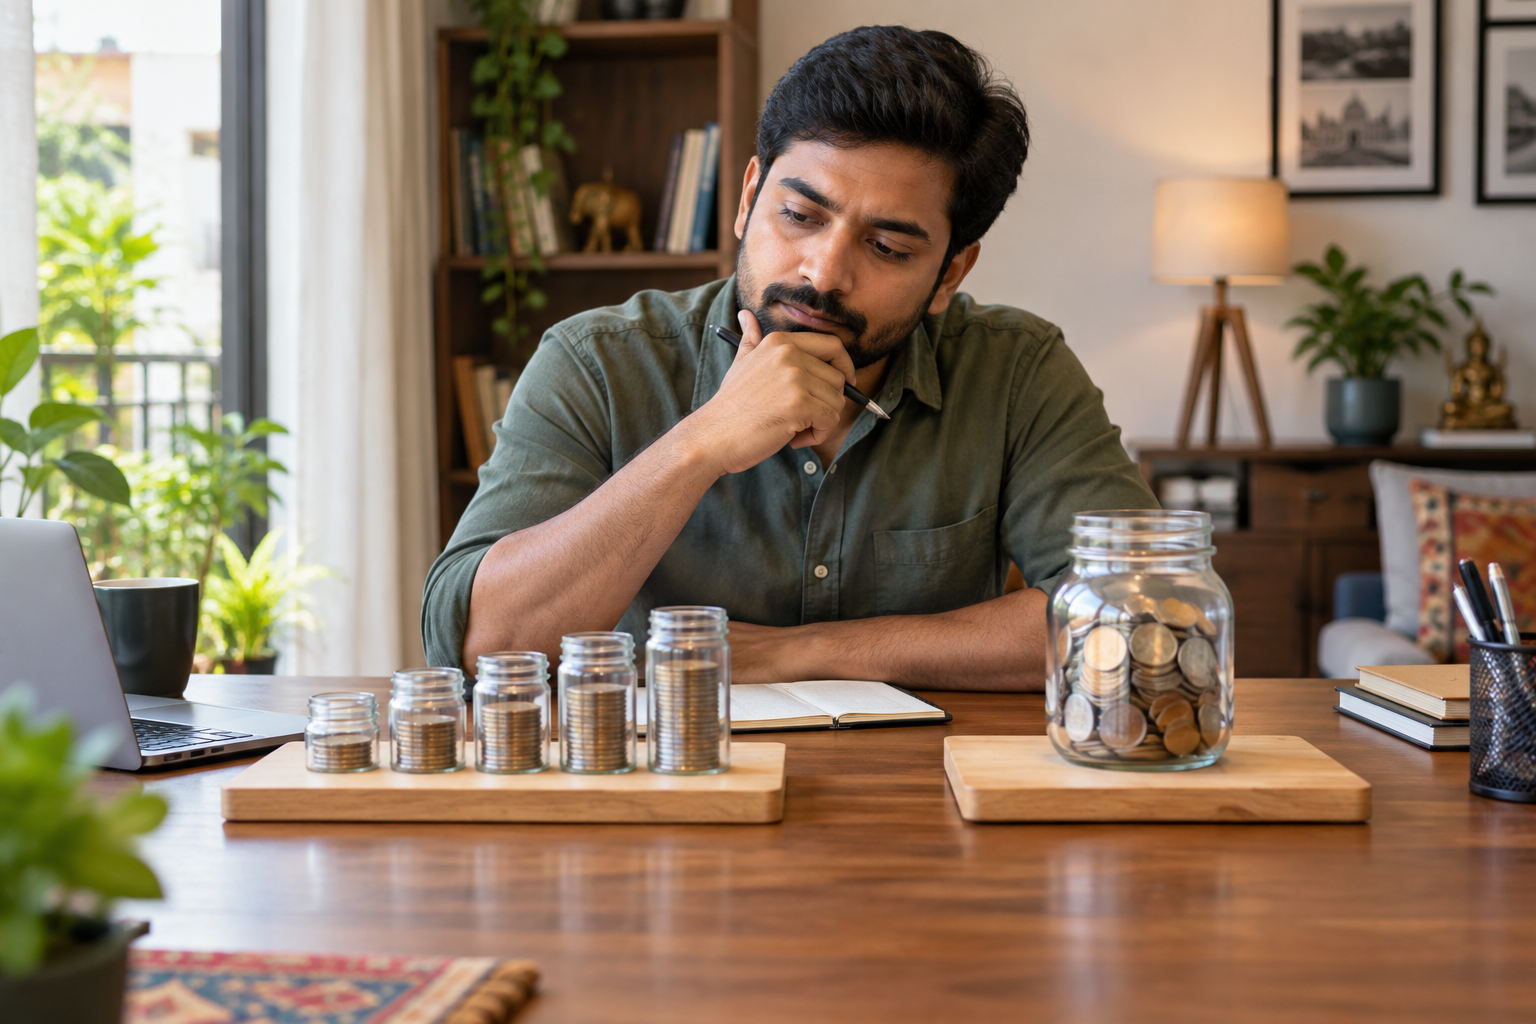
SIP involves investing a fixed amount periodically—usually monthly—into mutual funds, allowing investors to buy units at varying market prices over time. Lump sum means investing a substantial amount in one go, buying units all at once.
In India, mutual funds widely support SIPs to encourage disciplined saving. Lump sum investments might suit investors with available capital who want immediate exposure to market movements.
Which investment method is better for beginners: SIP or lump sum?
SIP is generally better for beginners as it encourages disciplined investing through fixed, periodic contributions and benefits from rupee cost averaging, which reduces the risk of investing at market highs. Lump sum investments require accurate market timing and higher risk tolerance, which beginners may lack.
Due to SIP’s manageable approach and reduced emotional stress, it helps new investors build confidence while staying invested consistently.
How does market volatility affect SIP vs lump sum investments?
SIP mitigates volatility by spreading investments over multiple market cycles, averaging purchase costs and reducing the impact of downturns. Lump sum investors face higher timing risk and may experience greater volatility, but can gain if invested before market upturns.
During market downturns, SIP’s staggered entry generally offers safer investing, whereas lump sum investing versus market swings can lead to larger short-term losses.
What are the advantages of SIP over lump sum in Indian mutual funds?
- Ability to start with small amounts, making investing accessible.
- Instills a disciplined savings habit and regular investment routine.
- Reduces emotional decision-making linked to market volatility.
- Benefits from rupee cost averaging, lowering overall investment cost.
When should an investor choose lump sum investments in India?
Investors may opt for lump sum when they have a large capital amount available and are comfortable with market risks. Those with higher risk tolerance and sufficient knowledge to assess market conditions may benefit more.
Lump sum is suitable for long-term investing horizons to absorb short-term volatility and capitalize on market growth.
What financial goals are more suited to SIP investments?
SIPs work well for systematic wealth creation aligned with mid- to long-term goals such as retirement planning and child education funds. They suit investors who need to manage income flow steadily and prefer regular investment discipline.
Are there tax benefits linked to SIP or lump sum investments in India?
Tax benefits relate to the mutual fund type rather than the investment method. For example, ELSS mutual funds offer tax deductions under Section 80C whether invested lump sum or via SIP. Capital gains tax treatment is identical for both methods, based on the holding period.
SIPs can help in timing gains for better tax planning but do not inherently provide tax benefits compared to lump sum investments.
How does the investment horizon influence the choice between SIP and lump sum?
Long-term investors with the ability to withstand market fluctuations may prefer lump sum to maximize growth potential. Shorter or uncertain investment horizons favor SIP, which reduces timing risks and spreads market exposure across different periods.
Your time frame directly impacts your risk tolerance and guides whether SIP or lump sum suits your investment strategy.
How do returns compare between SIP and lump sum investments over the long term?
Lump sum investments historically yield higher returns if deployed before a sustained market rise due to immediate full exposure. SIPs offer smoother returns, reducing the impact of market timing risks by averaging purchase prices over time.
The relative performance of SIP vs lump sum depends heavily on market cycles and entry timing.
Comparison Table: SIP vs Lump Sum Investments in India
| Attribute | SIP | Lump Sum |
|---|---|---|
| Investment Mode | Periodic fixed amounts (monthly/quarterly) | One-time upfront amount |
| Risk | Lower due to rupee cost averaging | Higher market timing risk |
| Best For | Beginners, disciplined savers, moderate risk appetite | Experienced investors, high risk tolerance |
| Flexibility | Start with small amounts and increase gradually | Requires large capital upfront |
| Returns | Smoother, less volatile | Potentially higher but variable |
| Tax Benefits | Same as lump sum for same fund types | Same as SIP for same fund types |
| Ideal Investment Horizon | Mid-to-long term with regular contributions | Long term suited to absorb volatility |
Frequently asked questions
Is SIP a safer option during market downturns?
Yes, SIP is generally safer because investments are spread over time and rupee cost averaging reduces the impact of investing at market highs. It lowers timing risk especially during volatile markets.
How does market volatility impact lump sum investments?
Lump sum investments are more exposed to market timing risk; entering before a downturn may lead to temporary losses. However, lump sum can yield higher returns if invested ahead of a sustained market uptrend.
What are the tax implications of SIP vs lump sum investments in India?
Tax treatment depends on the type of mutual fund and holding period, not on whether investment is lump sum or SIP. ELSS funds provide tax benefits under Section 80C regardless of the mode.
Which investment suits different investor risk profiles better: SIP or lump sum?
Investors with lower risk tolerance and beginners benefit from SIP’s discipline and risk mitigation. High-risk investors with market knowledge may choose lump sum to aim for higher returns.
Can SIP help in financial discipline and long-term wealth creation?
Yes, SIP encourages regular investing habits, helps in rupee cost averaging, and suits long-term wealth creation by making investing manageable and less stressful.
The bottom line
In India, SIP is ideal for investors seeking steady, disciplined wealth creation with lower risk and manageable contributions. Lump sum suits those with substantial capital and higher market risk appetite aiming for potentially greater long-term returns. Your choice should reflect your financial goals, risk tolerance, and investment horizon.
For more on managing finances securely, read about how much to save for an emergency fund in India and explore space-saving ideas for Indian homes.
Sources & methodology
We reviewed the primary references below when checking the time-sensitive facts in this guide. Product features, prices, rules and eligibility can change, so confirm important details with the linked authority before acting.
- SEBI Investor: mutual funds investor.sebi.gov.inRegulator-backed investor education about mutual funds.
- Association of Mutual Funds in India amfiindia.comIndustry reference explaining systematic investment plans.